World · Daily Terminal
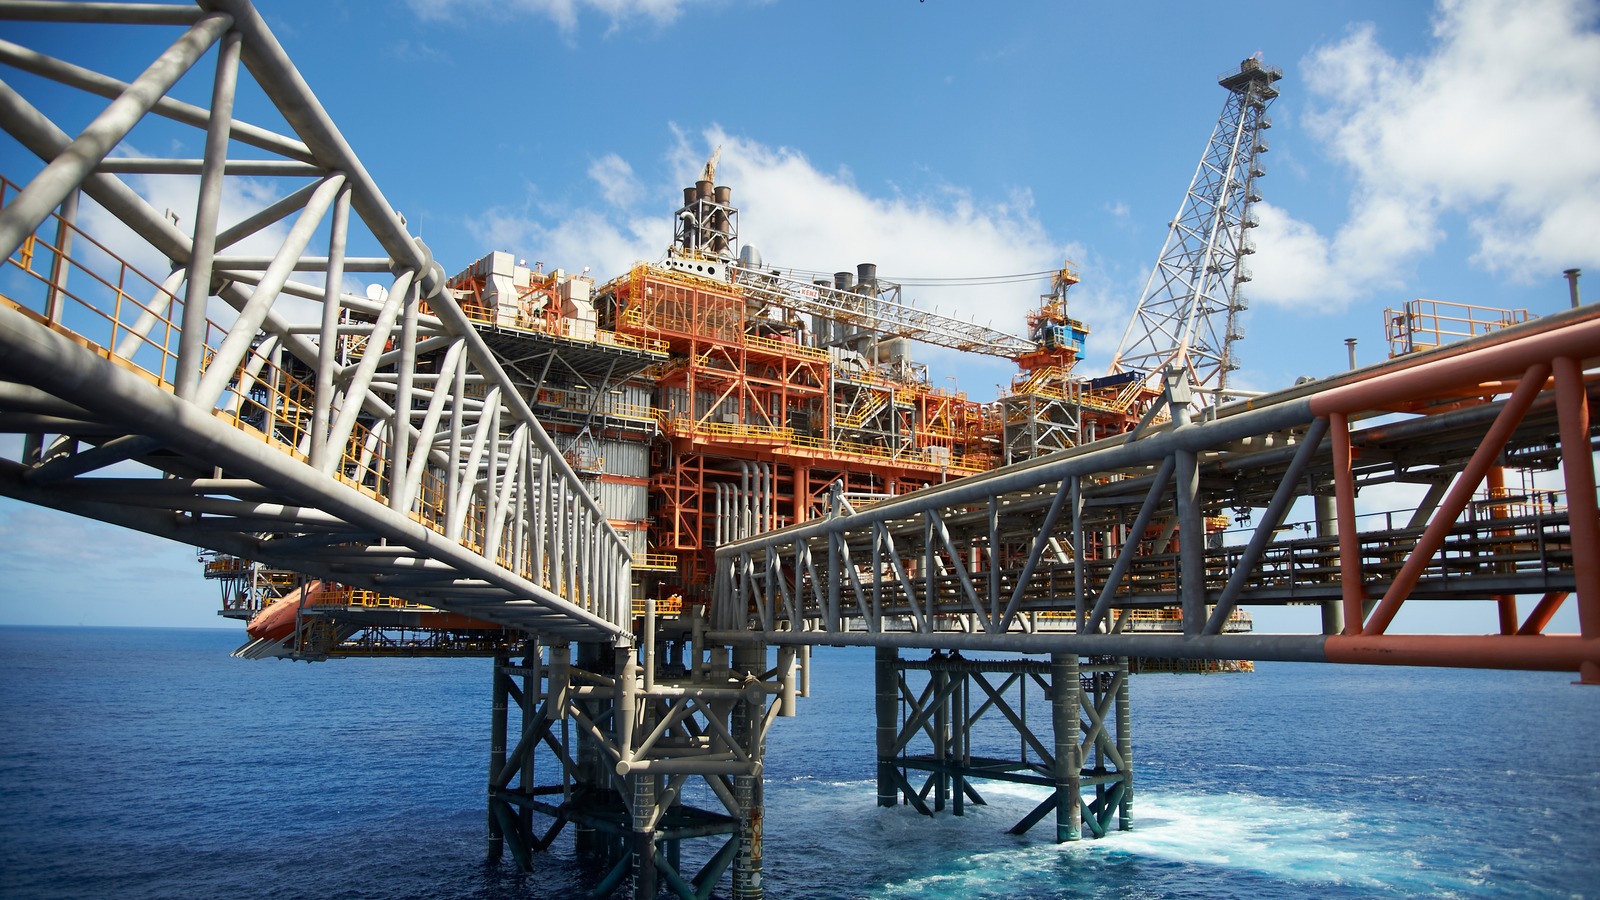
Woodside Energy Group reported unaudited Q3 2026 operating revenue of US$4.28b and year to date revenue of US$11.73b, with production and sales volumes modestly lower than a year earlier and full year production guidance adjusted to 174 to 185 MMboe. Progress on Scarborough LNG commissioning and centralisation of the Trion project in Mexico shows Woodside Energy Group concentrating execution around a few large LNG and deepwater hubs, while trimming exposure to projects such as Calypso and Beaumont New Ammonia. We will assess how Woodside Energy Group's Q3 revenue performance and revised production guidance may influence the investment narrative investors rely on.
Scan how Woodside Energy Group's LNG focused update compares with peers by sizing up hand picked 16 nuclear energy infrastructure stocks that are also tied to long term energy infrastructure build outs. Woodside Energy Group Investment Narrative Recap To own Woodside Energy Group, you need to believe its LNG heavy portfolio can keep generating strong cash through large, long life projects. In the short term, the story now revolves around Scarborough and Pluto Train 2 moving from build to production.
Q3 showed that revenue can remain solid even as volumes soften slightly, so the update does not radically change that thesis. The key near term catalyst is still first LNG from Scarborough and how quickly those volumes and cash flows ramp. The biggest immediate risk sits in execution timing and reliability on Scarborough, Trion and aging offshore assets like Okha.
Any further slippage in start up windows or operating efficiency would matter more than this quarter’s production tweak. The production guidance revision to 174 to 185 MMboe for 2026 is the cleanest read through for you. It slightly widens the range at the top end, reflecting lower expected volumes from Beaumont New Ammonia, Okha and a smaller Scarborough contribution before year end.
That adjustment keeps attention firmly on project delivery rather than demand. For catalysts, this matters because it tightens the link between Woodside’s share price story and on time commissioning. Each update on Scarborough cargo timing, Trion drilling progress or divestments like Calypso will now be judged against this guidance band.
The risk side is clear. If further revisions appear, investors will likely refocus on execution reliability and capital discipline. Woodside Energy Group's current analyst storyline points to revenue of $16.1b and earnings of $3.2b by 2029.
That profile assumes 5.1% yearly revenue growth and an earnings increase of about $0.1b from $3.1b today. Uncover why Woodside Energy Group's fair value is essentially consistent with its current price. ASX:WDS 1-Year Stock Price Chart Exploring Other Perspectives One alternate view puts Scarborough and Pluto Train 2 as the real swing factor for Woodside Energy Group.
The most optimistic analysts were pencilling in revenue of about $17.6b and earnings near $3.9b by 2029, compared with the consensus $16.1b and $3.2b. After this Q3 update and guidance tweak, those storylines may shift. Treat them as moving pieces rather than fixed outcomes, and explore a range of estimates before deciding what you believe.
Explore 6 other Woodside Energy Group fair value estimates , including one that suggests as much as 135% upside from the current price! The Verdict Is Yours Don't just follow the ticker; dig into the data and build a conviction that's truly your own. A great starting point for your Woodside Energy Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
See our latest analysis for Woodside Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodside Energy Group's overall financial health at a glance. Looking for more investment ideas beyond Woodside Energy Group?
Once you have a view on Woodside Energy Group, it often helps to line it up against a few other opportunities. The Simply Wall St Screener can help you quickly filter the market so you are not relying on a single story or sector. If you care most about quality at a sensible entry point, scan a curated set of 4 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them.
For income focused investing, compare Woodside's payout profile with a pool of 5 dividend fortresses that target yields of 5% or more, while aiming to keep the payment stream resilient. When capital preservation is near the top of your list, start with 6 resilient stocks with low risk scores to narrow in on businesses that score well on balance sheet strength and risk factors. Valuation is complex, but we're here to simplify it.
Discover if Woodside Energy Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition. Access Free Analysis Have feedback on this article? Concerned about the content?
Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Source: Simply Wall Street